


Charles Gaba is a health care analyst who tracks policy and politics at ACASignups.net. Subscribe to his Substack!
Welp. Welcome to TrumpCare 2.0: The subsidies have been gutted, anyone earning more than 4 times the federal poverty level is completely S.O.L., nearly anyone who isn’t a U.S. citizen has been thrown under the bus, and there’s more ugliness yet to come.
Even with all of this, however, the ACA isn’t quite dead yet: It still offers affordable coverage to many people (if far less affordable than it was a year ago), it still offers a lot of vitally important patient protections, and it’s still the only viable option for millions of Americans who are self-employed or who work for small businesses which don’t offer decent health coverage on their behalf.
So, with that in mind, it’s time once again to update my annual ACA Open Enrollment Period (OEP) Guide for 2027. Most of the Open Enrollment tips I give every year remain good advice, even if they kind of feel like slapping a Band-Aid® on a gaping gunshot wound this year.
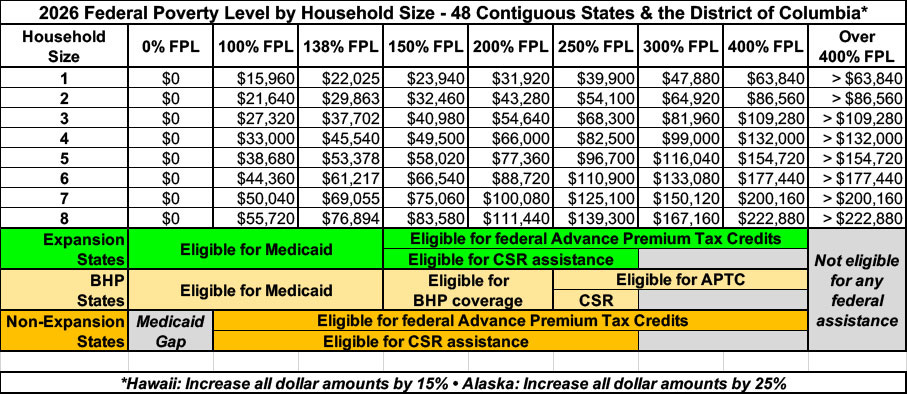
Before I begin, it’s extremely important to know what the Federal Poverty Level (FPL) will be in 2027. The FPL is a critical part of the formula used to determine eligibility for both premium tax credits as well as Cost Sharing Reduction (CSR) subsidies and Medicaid expansion eligibility in the states which have expanded the program. In addition, the FPL threshold goes up by a few percent each year due to inflation.
The table below breaks out the key annual income levels for different FPL thresholds based on the number of people in the household. Note that all of these levels are 15% higher in Hawaii and 25% higher in Alaska.
With all of that in mind, here’s some important things to know when you go to #GetCovered.
1. DON’T MISS THE DEADLINE!
The 2027 Open Enrollment Period officially runs from November 1st, 2026 through January 15th, 2027 in most states, but there are some exceptions at both ends.
California doesn’t launch their 2027 OEP until November 1st, but current enrollees have been able to actively re-enroll for 2027 since October 1st. California’s OEP runs through January 31st, 2027.
Connecticut starts their 2027 OEP on October 23rd.
The District of Columbia’s OEP runs through January 31st, 2027.
Idaho already started their 2027 OEP on October 15th, and it only runs through December 15th.
Massachusetts starts their 2027 OEP on October 23rd, and it runs through January 23rd, 2027.
New Jersey’s OEP runs through January 31st, 2027.
New York’s OEP runs through January 31st, 2027.
Rhode Island’s OEP runs through January 31st.
Virginia’s OEP runs through January 29th, 2026.
In most states, you have to enroll by December 15th in order for your coverage to start on January 1st; otherwise it won’t start until February 1st. However, there’s a few exceptions:
Idaho: The December 15th deadline is the ONLY one (no February-start eligibility!)
Massachusetts: December 23rd for January 1st coverage
California, Maryland, Nevada, New Jersey, New Mexico and Rhode Island: December 31st for January 1st coverage
Here’s the official deadlines for coverage starting February 1st for every state:
California: January 31st
District of Columbia: January 31st
Idaho: n/a (Special Enrollment only)
Massachusetts: January 23rd
New Jersey: January 31st
New York: January 31st
Rhode Island: January 31st
Virginia: January 29th
ALL OTHER STATES: January 15th
There are some important exceptions to the above deadlines, however: Some people are eligible to enroll in coverage year round:
Members of federally-recognized Native American tribes or Alaska Natives can enroll in ACA coverage year round.
There are several state-specific programs which allow eligible enrollees to do so year round, including:
Connecticut: Covered Connecticut
District of Columbia: Healthy DC (Basic Health Plan)
Massachusetts: ConnectorCare
Minnesota: MinnesotaCare (Basic Health Plan)
New York: Essential Plan (Basic Health Plan)
Oregon: Bridge Program (Basic Health Plan)
In addition, people who are eligible for Medicaid or the Children’s Health Insurance Program (CHIP) are eligible to enroll in those programs year-round.
If you want to enroll outside of the dates above and aren’t eligible for any of the exceptions listed, you’ll likely have to qualify for a Special Enrollment Period (SEP).
Qualifying Life Experiences (QLEs) which make you eligible for a SEP include things like:
Losing employer-sponsored healthcare coverage
Getting married or divorced
Giving birth/adopting a child
Turning 26 and having to move to your own policy
Losing eligibility for Medicaid or CHIP
Moving out of your current rating area
2. ONLY ENROLL VIA AN OFFICIAL ACA HEALTH EXCHANGE OR AN AUTHORIZED ENROLLMENT PARTNER.
ACA financial subsidies are only available to eligible enrollees who sign up through an official ACA exchange or an authorized 3rd-party exchange entity, known as an Enhanced Direct Enrollment (EDE) entity.
There’s a ton of junk plans and scam artists out there, especially these days. Fraudulent plans are being hawked endlessly via both robocalls, spam emails and fly-by-night websites.
IMPORTANT: Scams and Junk Plan pitches are an even worse problem these days due to both the expired tax credits as well as other Trump regime policy changes which have made it more difficult for people to enroll in legitimate ACA plans or to qualify for financial help.
If you’re enrolling online, make sure to use one of the official ACA exchange websites:
OREGON: ExplORe Health (new!)
As for EDEs, it’s important to note that some of these may also sell non-ACA compliant plans. The largest EDE, HealthSherpa, only sells on-exchange ACA-compliant policies.
Also note that while some insurance carrier websites are also hooked into the federal exchange via an EDE, they (understandably) only list their own plans. I still recommend only using one of the websites listed above. Remember, whether via an official exchange site or an EDE, you have to enroll on-exchange to be eligible for financial help!
3. DOUBLE-CHECK YOUR 2027 INCOME TO SEE IF YOU’RE ELIGIBLE FOR FINANCIAL HELP.
As i note in the table above, the household Federal Poverty Level (FPL) threshold is critical in determining whether or not you’re eligible for Advanced Premium Tax Credits (APTC) as well as Cost Sharing Reduction (CSR) assistance...and while the enhanced tax credits expiring last year means that APTC levels are far less generous across the board, there’s still at least some level of financial help available for most enrollees.
Here’s the APTC income eligibility sliding scale for 2027 for households at various income brackets compared to the formulas in 2025. As you can see, the subsidy formula has become far less generous due to the expiration:
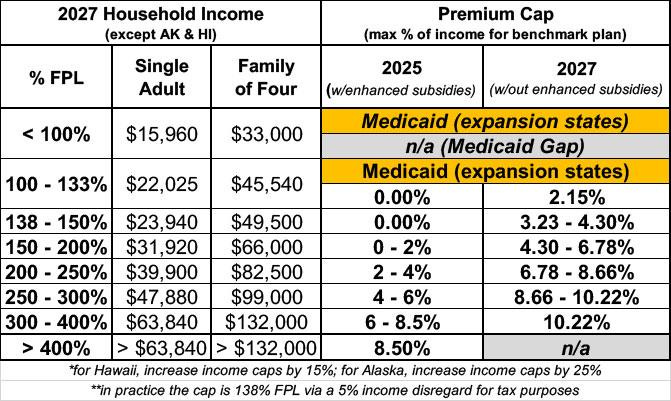
For example: $40,000/year for a single adult was 266% FPL in 2025 but will only be around 251% FPL in 2027.
A single adult who earns exactly $40,000 each year only had to pay around 4.6% of their income for the benchmark Silver plan in 2025 (~$153/month) ... but in 2027, they’ll have to pay around ~8.7%, or roughly $290/month.
A family of four which only had to pay 2% of their income in premiums for the benchmark plan in 2025 will have to pay 3.4x as much next year (6.8% of their household income), and so on.
The bottom line is that in 40 states plus D.C., if your household income is less than 138% FPL, you should be eligible for Medicaid; if you earn between 138 - 400% FPL, you should be eligible for subsidized ACA exchange coverage; and if you earn more than 400% FPL you’re only eligible for ACA exchange coverage at full price.
4. IF YOU EARN MORE THAN 400% FPL, THERE ARE WAYS TO LEGALLY GET YOUR 2026 MAGI INCOME BELOW THE SUBSIDY CLIFF THRESHOLD.
I’m neither an accountant nor a tax attorney, but there are several perfectly legal ways for people with incomes over the 400% FPL “subsidy cliff” threshold to push their household back below the cut-off level so that they’ll remain eligible for ACA tax credits after all (you can also use these to increase your subsidy even if you’re already below 400% FPL, for that matter).
From my friend and colleague Louise Norris:
A lower income and more adjustments to income will reduce MAGI. You should consult your tax advisor to consider the available deductions/adjustments on your tax return that are above the line that shows your AGI since reductions to your AGI will also reduce your ACA-specific MAGI.
Tax-deductible contributions to a traditional individual retirement account (IRA) will reduce your ACA-specific MAGI. Your tax advisor should be able to explain the details of this to you, including how to determine whether you’re eligible to make tax-deductible contributions to a traditional IRA.
In addition, your tax advisor can explain how contributing to an employer-sponsored pre-tax retirement plan like a 401(k) will lower your ACA-specific MAGI.
… If you’re self-employed, your tax advisor can advise whether it is in your best interest to set up a self-employed retirement plan such as a SEP IRA, SIMPLE IRA, or Solo 401(k). Talk with your tax advisor to see if one makes sense for you. Keep in mind that these retirement plans for self-employed people have contribution limits that are potentially higher than those of traditional IRAs allowing people to reduce their MAGI by a larger amount than a traditional IRA would allow.
If you have an HSA-eligible high-deductible health plan (HDHP), contributions to an HSA will reduce your ACA-specific MAGI. Your tax advisor should be able to answer any questions you have about this. It’s important to note that starting with the 2026 plan year, all Bronze and catastrophic plans purchased in the health insurance Marketplace will be considered HDHPs. So if you enroll in one of these plans, you’ll be eligible to contribute to an HSA, as long as you don’t have any additional major medical coverage.
Self-employed people may also deduct their health insurance premiums, which may lower their MAGI, but it gets a bit complicated if that’s the factor that makes you eligible for a premium subsidy.
5. HOWEVER, BE CAREFUL, BECAUSE THERE’S NO LONGER A CAP ON HOW MUCH YOU HAVE TO PAY BACK IF YOU UNDERESTIMATE YOUR INCOME...
Until this year, there’s been a limit on how much of their federal tax credits ACA enrollees have to pay back to the federal government if they underestimated their annual household income...which is to say, if they overestimate the amount of tax credits they were technically eligible for.
Up through the 2025 tax year, enrollees whose household income ended up being less than 200% FPL only had to pay back a maximum of $375 if they were single or up to $750 for any other tax filing status.
If they earned between 200 - 300% FPL, they’ve been limited to paying back no more than $975 if they’re single or $1,950 for any other filing status.
And if they earned between 300 - 400% FPL, they were limited to paying back no more than $1,625 if single or $3,250 for other filing statuses.
If their MAGI income was over 400% FPL, however, they’ve had to pay whatever the excess APTC ends up being.
HOWEVER, starting with the 2026 calendar year, there will no longer be ANY caps on what portion of excess APTC has to be repaid, regardless of what your income bracket is.
If you overestimate your tax credits by $1,000, you’ll have to pay back $1,000. If you overestimate by $5,000, you have to pay back all $5,000. And if you think you’ll end up below that 400% FPL threshold but end up with a 2026 MAGI of 401% or higher...you’ll have to pay back every dime, which could potentially be $10,000 or more.
So proceed with the HSA/IRA ideas laid out in #4 above with caution.
That’s it for Part 1. I’ll be back next week with Part 2 of my ACA Open Enrollment Period guide.
Thank you for the information, Mr. GABA. I have seen a lot of serious health issues with the elderly. They can’t get the care they need.